

De-Dollarization in 2026:
What’s Actually Happening
vs. What Gets Hyped
The dollar’s reserve share has fallen from 72% to 56% over two decades. BRICS Pay just got pushed from 2026 to 2030. Both facts are true, and neither means what most coverage says it means.
FX reserves, Q2 2025
(down from 72% in 2001)
share of global reserves
(IMF COFER, Q2 2025)
BRICS Pay operational
(from earlier 2026 estimates)
when adjusted for FX
movements, Q2 2025
There’s a version of this story that writes itself: BRICS is rising, the dollar is dying, and your business had better pivot to yuan before 2027 or get left behind. That version gets clicks. It also gets the timeline wrong by roughly a decade.
Here’s the honest version. The dollar is declining as a share of global reserves — that’s real, it’s been happening for twenty years, and it has meaningful implications. BRICS Pay is under development — that’s also real, with a prototype demonstrated in Moscow in October 2024. But the operational target just got pushed from 2026 to 2030 by Russia’s own deputy foreign minister. A unified BRICS currency remains, in the words of experts from Brazil to Russia, at least a decade away after that.
Both things are true simultaneously. The structural shift is real and worth understanding. The timelines are slower, messier, and more contested than the breathless coverage suggests. That tension — between genuine change and overhyped pace — is the actual story.
The Dollar’s Reserve Share: What the IMF Data Actually Shows
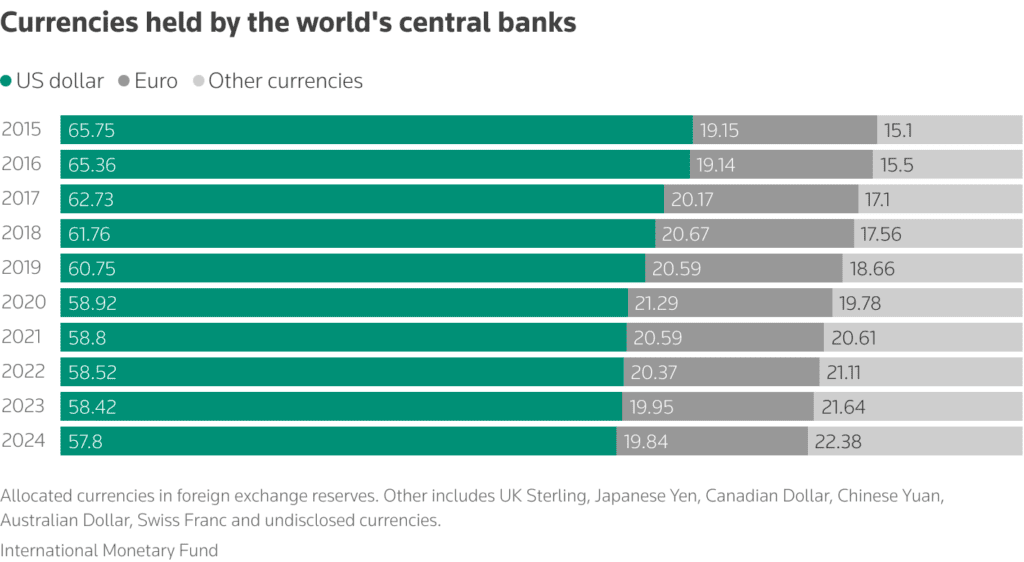
Start with the numbers most cited and least explained. The IMF’s COFER database — the most authoritative source on global reserve currency composition, reported quarterly by 149 economies — put the dollar’s share at 56.32% in Q2 2025. IMF COFER, published October 2025. Data are voluntary and confidential at the country level; aggregate figures are authoritative.
That’s down from 72% in 2001. It sounds dramatic. Here’s what the IMF itself noted about Q2 2025 data that almost no one reported: once adjusted for exchange rate movements, the dollar’s share declined by only 0.12 percentage points that quarter — nearly all of the apparent decline was a valuation effect, not central banks actively selling dollars. IMF Blog, “Dollar’s Share of Reserves Held Steady in Second Quarter When Adjusted for FX Moves,” October 2025. Primary source.
The Federal Reserve’s 2025 edition of “The International Role of the US Dollar” is even blunter. The dollar is far ahead of every alternative: dollar at 58%, euro at 20%, yen at 6%, pound at 5%, renminbi at 2%. The gains in “other currencies” over twenty years don’t flow to the yuan. They’ve gone to Australian and Canadian dollars, the Swiss franc, and a basket of smaller currencies. The renminbi has been stuck at roughly 2% of global reserves since the IMF began tracking it separately in 2016. It hasn’t moved.
The twenty-year decline from 72% to 56% is real. It happened. But it didn’t flow to China. It flowed to diversification across a basket of currencies nobody headlines. And the Federal Reserve’s analysis concludes the dollar retains structural advantages — depth of capital markets, institutional stability, dollar-denominated commodity pricing — that are genuinely hard for any alternative to replicate quickly. Not impossible to replicate. Hard.
The dollar erosion is multi-decade and structural, not imminent and sudden. It has meaningful portfolio implications for businesses with significant cross-border exposure — but those implications are about gradual diversification and currency risk management, not about emergency pivots to yuan-denominated contracts by next quarter. Any advisor telling you otherwise is selling something.
BRICS Pay: The Real Status, As of April 2026
The original article claimed BRICS Pay would be “fully rolling out by 2026, potentially capturing 20% of international commerce.” That’s not where things stand.
GIS Reports, as of mid-2025: the system remains in planning and early pilot stages. The prototype demonstration in Moscow in October 2024 was a real technical milestone — blockchain-based, decentralized messaging, designed to link national payment systems without requiring the dollar as intermediary. But no fully unified BRICS payment system currently exists. Russia’s SPFS and China’s CIPS serve as the main alternatives to SWIFT for their bilateral trade, but they don’t yet interoperate seamlessly with each other, let alone with India’s UPI or Brazil’s Pix. GIS Reports, October 2025. Independent policy analysis organization.
In October 2025, Russian Deputy Foreign Minister Sergey Ryabkov explicitly clarified that BRICS Pay is now targeted for operational status by 2030 — not 2026. EBC Financial Group, citing Ryabkov statement October 2025. Confirmed across multiple sources. Russia’s own foreign minister had said a pilot could appear “before the end of 2026,” but even that was characterized as aspirational. And in February 2026 in New Delhi, under India’s BRICS chairmanship, discussions still focused on the payment infrastructure architecture rather than launch timelines.
There’s a clarification worth making explicit, because the original article conflated these: the current BRICS initiative is not trying to create a single currency. Earlier proposals along those lines faltered because of divergent inflation regimes, incompatible capital controls, and member states’ concern about Chinese yuan dominance in any unified system. The current approach links existing national CBDCs — India’s digital rupee, China’s digital yuan, Russia’s digital ruble — through interoperable infrastructure. Each currency remains fully sovereign. The ambition is a payment rail, not a new reserve currency.
“No unified BRICS currency will be released in the near term. BRICS Pay, once expected to pilot by late 2026, is now targeted for operational status by 2030. Any euro-style currency union sits a decade or more beyond that.”
EBC Financial Group analysis, October 2025 update — full analysisWhat’s Real, What’s Already Happening, and Why It Matters Anyway
Here’s where the story gets genuinely interesting and genuinely underreported. 90% of intra-BRICS trade now settles in local currencies, up from 65% two years prior. EBC Financial Group, April 2026. Primarily reflects Russia-China bilateral trade driven by sanctions. Not generalizable to all BRICS member pairs equally. Russia-China energy trade essentially bypasses the dollar entirely. Gold’s share of official reserve assets has more than doubled from below 10% in 2015 to over 23% now — though the Federal Reserve notes this mostly reflects gold’s price appreciation rather than central banks actively buying more gold in physical terms.
The yuan’s share of SWIFT transactions has grown. China’s CIPS system processed significantly higher RMB transaction volumes in 2024 than in prior years. None of this adds up to dollar displacement at the global level. What it adds up to is a parallel system developing alongside the existing one — primarily serving sanctioned or sanction-adjacent economies and China’s bilateral trade relationships.
Read the IMF’s exchange-rate-adjusted COFER data, the Federal Reserve’s reserve currency analysis, and the GIS Reports BRICS Pay status update together. The conclusion that emerges: de-dollarization is two simultaneous phenomena being conflated into one. The first is genuine long-run diversification away from the dollar across the global central bank community — real, twenty years in progress, likely to continue. The second is sanctions-driven bilateral workarounds, primarily between Russia, China, Iran, and their trading partners — also real, but structurally different. The first has no clear BRICS catalyst. The second has BRICS architecture as a vehicle. Conflating them produces forecasts that are wrong in both directions: too alarmist about dollar collapse, too dismissive about the structural shift that’s actually occurring.
| Claim Often Made | What the Evidence Shows | Source Quality | ⚠ The Complication |
|---|---|---|---|
| “The dollar’s reserve share is collapsing” | It declined from 72% (2001) to 56% (Q2 2025) — real, but slow. Exchange-rate-adjusted Q2 2025 actual decline: 0.12 percentage points. | Strong — IMF COFER, primary source, 149 reporting economies | Most apparent quarter-to-quarter movement is valuation effect, not active portfolio shift. The IMF explicitly flags this. It’s rarely reported. |
| “China’s yuan is taking over” | Renminbi is 2.12% of global reserves (Q2 2025). Unchanged since 2016 when IMF began tracking separately. | Strong — IMF COFER, primary source | Dollar diversification has primarily benefited Australian/Canadian dollars, Swiss franc, and basket of smaller currencies — not the yuan. Capital controls and limited RMB bond market liquidity are structural constraints. |
| “BRICS Pay launches in 2026” | Prototype demonstrated October 2024. Operational target revised to 2030 by Russia’s own deputy FM in October 2025. | Strong — GIS Reports, EBC analysis, Ryabkov statements; consistent across sources | Even the 2030 target is aspirational. Technical interoperability between SPFS, CIPS, UPI, and Pix remains partially implemented. Cybersecurity frameworks and messaging standards still under development. |
| “90% of intra-BRICS trade avoids the dollar” | Primarily reflects Russia-China bilateral trade under sanctions pressure, not evenly distributed across BRICS member pairs. | Moderate — directional, sourcing concentrates in EBC and similar financial analytics; not independently audited | This figure cannot be generalized to BRICS-wide dollar avoidance. Brazil-India trade, for example, still largely dollar-denominated. Context of sanctions matters. |
| “BRICS will launch a unified currency” | Current BRICS initiative explicitly does not seek a unified currency. It seeks interoperable CBDC infrastructure with sovereign national currencies. | Strong — Asia Times, GIS Reports, Putin December 2025 statement (“should not be rushed”); consistent | Even the payment rail is a decade away. An euro-style currency union requires monetary policy convergence BRICS members have explicitly declined to pursue. India and China having competing border disputes makes this structurally difficult. |
What to Actually Do — By Audience
Gradual diversification is warranted. Emergency pivots are not.
The twenty-year trend in dollar reserve erosion is real and likely to continue. For companies with significant exposure to BRICS economies — particularly China, India, and Gulf states — monitoring non-dollar settlement options is reasonable risk management. The yuan’s SWIFT share is growing (toward 8.5% of global forex trades by September 2025, per EBC data). EBC Financial, April 2026. Yuan forex transaction share is not the same as reserve currency share — different measures, different significance. China’s CIPS system is a legitimate settlement alternative for RMB-denominated transactions.
What you do: Review your cross-border transaction exposure by currency and payment rail. If you have material Russia or Iran exposure (unlikely for most Western companies post-sanctions), the SWIFT-alternative question is already being answered for you by compliance. For China exposure: understand whether your contracts are RMB or dollar-denominated and what your counterparty risk looks like in a scenario where payment systems fragment further. This is general business guidance, not financial advice. Consult a qualified financial advisor for specific hedging strategies.
Local currency contracts and CBDC pilots are real opportunities now
While the global reserve story is slow-moving, the on-the-ground reality for businesses in BRICS markets is moving faster. China’s e-CNY (digital yuan) is live and integrated across major Chinese e-commerce platforms. India’s digital rupee pilot has expanded to wholesale transactions. Brazil’s Pix instant payment system processed over 4 billion transactions in 2024. These are not hypothetical — they’re live infrastructure you can integrate with today if you operate in those markets.
For businesses doing significant volume in China: accepting e-CNY settlement and understanding CIPS as an alternative to dollar correspondent banking for RMB transactions are worth evaluating now. For India operations: Pix-equivalent UPI international expansion is actively developing. These are market-specific infrastructure plays, not a de-dollarization thesis.
Gold’s move is real; the yuan thesis is premature
The Federal Reserve’s data shows gold’s share of official reserve assets more than doubled since 2015 — from below 10% to over 23%. Federal Reserve, July 2025. This mostly reflects price appreciation (gold rose 60–70% in 2025 alone, exceeding $5,500/oz in early 2026) rather than central banks massively increasing physical gold holdings. The physical quantity of gold holdings increased less than 10% over the same period. But the central bank accumulation trend is real — particularly China, Russia, and Turkey — and it’s not stopping. That tells you something about confidence in dollar-denominated assets at the margin.
For fintech investors: BRICS Pay’s confirmed blockchain architecture has practical implications for firms building on distributed ledger infrastructure for cross-border settlement. The 2026 India summit is the next meaningful catalyst to watch for progress signals. The 2030 target gives you a planning horizon — not an urgency timeline.
The Honest Forecast
The dollar isn’t dying on any near-term horizon. The WEF’s January 2025 consensus of leading economists and central bankers: “while gradual diversification away from the dollar may occur, there is little prospect of a major challenge to its supremacy.” World Economic Forum Annual Meeting, January 2025, via BestBrokers analysis. Consensus framing, not direct quote from named individual.
But. The twenty-year trend is real, not manufactured. A world where the dollar holds 56% of reserves instead of 72% is a world where dollar hegemony is meaningfully reduced even if no alternative dominates. A payment system targeting 2030 operational status is still a payment system being built. India hosting the 2026 BRICS summit creates a genuine pressure point for progress — India has the most credibility as a neutral broker among BRICS members, and the most to gain from a payment system that isn’t driven by either Chinese or Russian interests.
The structural shift is happening. It’s happening slowly, unevenly, and on a timeline that makes most “pivot to BRICS by 2027” advice somewhere between premature and fiction. Watch the 2026 India summit. Watch the 0.12% vs. headline COFER numbers. Watch whether e-CNY adoption spreads outside China’s borders.
That’s the actual signal. Everything else is noise dressed in urgency.
Sources — All Primary or Named Independent
- IMF COFER Data Brief, Q2 2025. October 2025. Dollar share: 56.32%. Exchange-rate-adjusted actual decline: 0.12 percentage points.
- IMF Blog. “Dollar’s Share of Reserves Held Steady in Second Quarter When Adjusted for FX Moves.” October 2025.
- Federal Reserve. “The International Role of the US Dollar, 2025 Edition.” July 2025. Dollar at 58% of disclosed reserves; yuan at 2%; gold share doubled since 2015.
- GIS Reports. “BRICS Making Progress on Payment System.” October 2025. Status: early pilot stage, interoperability partially implemented.
- EBC Financial Group. “When Will BRICS Currency Be Released?” April 2026. Ryabkov 2030 target, 90% intra-BRICS local currency settlement figure.
- Asia Times. “BRICS Laying First Tracks for New Global Payment System.” February 2026. CBDC interoperability approach vs. unified currency.
- Wikipedia. BRICS Pay. History from 2018 launch; October 2024 China backing; Kazan Declaration.
- TV BRICS. “BRICS Payment System: What Experts Say.” March 2026. Expert assessments on timelines and mechanisms.
- Banking Frontiers. “BRICS Pay: The Slow Creation of a Global Currency.” November 2025. Rio 2025 summit outcomes.
- BestBrokers. “US Dollar Share of Global Currency Reserves.” Updated November 2025. Historical COFER data compilation; IMF primary source.
- South African Journal of International Affairs. “The BRICS, the Dollar and SWIFT: A Review of Evolving Interests and Monetary Reform Momentum.” 2025. Peer-reviewed academic analysis of BRICS monetary reform history.
Internal links: BRICS analysis hub · CBDC deep-dive · Dollar dominance tracker · China payment systems guide
https://www.futurenow.click/blog/
What Happens When Cash Completely Disappears?
Why AI Will Reshape Banking by 2030—Precision Agentic Transformation